
Market Overview
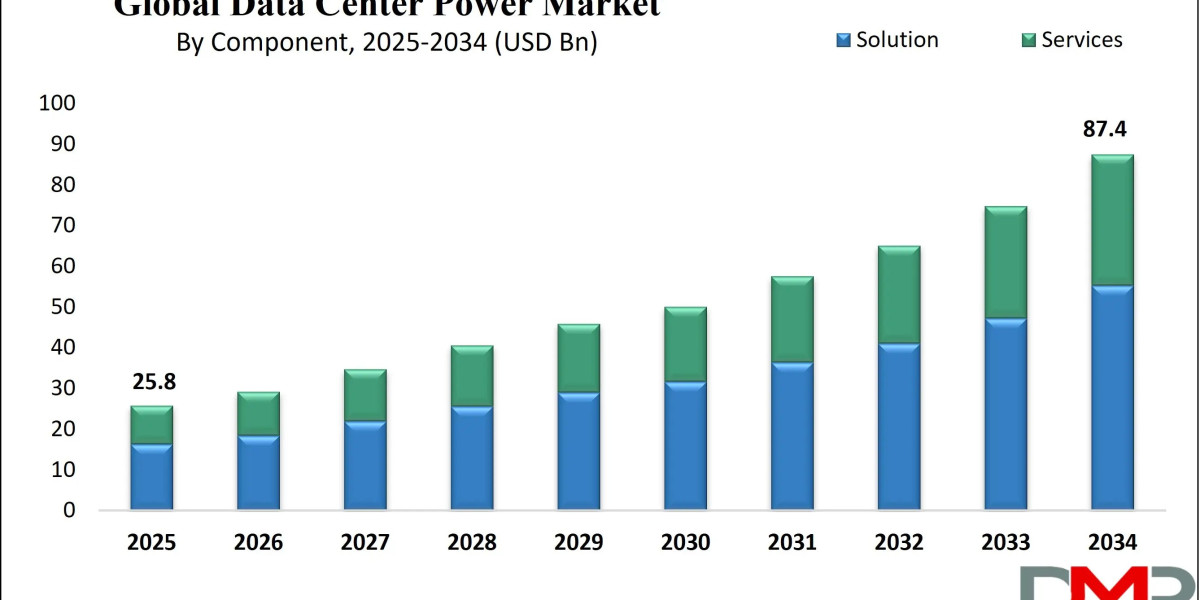
According to Dimension Market Research, the Global Data Center Power Market is projected to reach USD 25.8 billion in 2025 and grow at a compound annual growth rate of 14.5% from there until 2034 to reach a value of USD 87.4 billion. The market is witnessing robust growth due to the exponential rise in data processing needs, the rapid expansion of hyperscale and AI data centers, and the growing demand for reliable, efficient, and scalable power infrastructure across cloud, colocation, and edge environments.
The global data center power market is witnessing accelerated evolution driven by hyperscale expansion, surging data volumes, and demand for real-time services. With global data usage projected to exceed 180 zettabytes by 2025, the reliability and scalability of power infrastructure have become paramount in supporting digital transformation initiatives. Mission-critical environments such as cloud-native facilities, AI data lakes, and high-frequency trading platforms demand uninterruptible power systems (UPS), intelligent power distribution units (PDUs), modular busways, and grid-tied backup generators to maintain continuity and prevent latency or failure events.
One of the major trends reshaping the market is the pivot toward sustainable and energy-efficient power systems. Organizations are shifting to green data centers powered by renewables such as wind, solar, and hydrogen fuel cells. Lithium-ion batteries and flywheel-based UPS systems are replacing legacy lead-acid setups to ensure space efficiency and long battery life. Smart grid integration, dynamic load balancing, and real-time power analytics are enabling automated control and predictive maintenance in high-density environments.
However, the market faces significant restraints such as high energy consumption, increasing operational costs, and stringent regulatory compliance around carbon emissions. Global data centers currently consume over 200 terawatt-hours annually, prompting pressure from environmental regulators and international climate accords. Smaller operators find it challenging to scale power systems while remaining cost-efficient and carbon-neutral.
Definition and Market Significance
Data center power refers to the comprehensive infrastructure systems—including uninterruptible power supplies (UPS), power distribution units (PDUs), generators, busways, cabling, and monitoring software—that ensure reliable, efficient, and scalable electricity delivery to data center equipment. These systems protect servers, storage, and networking devices from power fluctuations, outages, and quality issues.
The importance of data center power lies in its critical role in maintaining uptime, preventing data loss, and enabling continuous operation of digital services. Without robust power infrastructure, even brief interruptions can lead to significant financial losses, service disruptions, and reputational damage for organizations relying on cloud computing, AI, and real-time applications.
Data center power also supports broader sustainability goals by enabling energy efficiency, integration of renewable sources, and compliance with environmental regulations. Modern power systems incorporate intelligent monitoring, predictive analytics, and software-defined controls to optimize energy usage and reduce carbon footprints.
Request a Complimentary PDF Sample
https://dimensionmarketresearch.com/request-sample/data-center-power-market/
Market Drivers
A major factor driving the Data Center Power Market is the advancement of virtualization and software-defined technologies. Organizations are shifting from traditional hardware-driven architectures toward software-centric models that offer greater agility, scalability, and centralized management, enabling rapid provisioning of resources, dynamic traffic control, and cost-efficient operations.
The growth of hyperscale and edge data centers is another key driver supporting market expansion. Hyperscale operators require ultra-high-capacity, energy-efficient, and automated power systems to manage massive workloads, while edge data centers support low-latency applications requiring compact yet high-performance power architectures.
The surge in AI/ML workloads further boosts demand for adaptive power systems capable of handling unpredictable, high-density data flows, driving investment in 400G/800G switches, intelligent traffic management systems, and automated power orchestration. Government incentives and energy efficiency regulations worldwide are also contributing to market growth by promoting sustainable power solutions.
Market Trends
The shift toward network automation and AI-driven operations is emerging as an important trend in the data center power market. AI-driven analytics, intent-based networking, and automated orchestration are transforming traditional workflows by reducing manual intervention, improving visibility, optimizing routing, and enhancing overall performance.
Another significant trend is the adoption of high-speed Ethernet and fabric architectures. The shift toward 400G and 800G technologies, along with advanced fabric networking, delivers the bandwidth and low-latency performance needed to support AI, big data analytics, and hyperscale cloud workloads.
The growing focus on energy-efficient and sustainable power solutions is also reshaping the market, influenced by global regulations and carbon-reduction commitments, driving interest in optimized power equipment and green data center initiatives.
Market Restraints
Despite its strong growth potential, the data center power market faces certain limitations. High capital and operational costs, including implementation of high-capacity power systems, advanced distribution solutions, and automation platforms, pose significant restraints, particularly for small and mid-size enterprises.
The skills shortage and complex power management present another challenge. Skilled professionals knowledgeable in software-defined power, automation, high-speed switching, and multi-cloud integration are in short supply globally, slowing deployment and increasing reliance on outsourcing.
In addition, managing hybrid environments that combine legacy hardware with modern software-defined components creates operational complexities, making security, performance, and stability across distributed data centers more challenging.
Market Opportunities
The expansion of AI and high-performance computing workloads presents a major opportunity for the data center power market. These workloads require high-bandwidth, ultra-low-latency, and highly resilient power environments, driving demand for advanced power systems, intelligent energy management, and automated orchestration.
The growth of edge and modular data centers creates substantial opportunities for power vendors. Edge facilities require compact, energy-efficient, and high-performance power solutions to support distributed computing, 5G applications, IoT analytics, and real-time AI processing.
Furthermore, the rise of remote industrial automation, autonomous transport, and smart city applications accelerates demand for decentralized digital ecosystems, offering significant growth potential for vendors providing flexible and scalable power solutions.
Segmentation
The Data Center Power Market is categorized based on component, technology, data center type, application, and end user.
By component, the solution segment is anticipated to lead with approximately 62.0% of the market share in 2025, driven by the essential role of UPS systems, PDUs, generators, busways, and cabling in delivering foundational power connectivity.
By technology, software-defined power and intelligent power management leads with an approximate 58.0% share in 2025, reflecting widespread adoption of programmable and centrally managed power networks across enterprises and service providers.
By data center type, hyperscale data centers dominate with a significant 60.0% share in 2025, driven by the explosive growth of cloud computing, AI, and large-scale digital platforms requiring extremely high-capacity, low-latency power infrastructure.
By application, IT and cloud workloads hold the largest share at approximately 54.0% in 2025, driven by the rapid expansion of cloud-native applications, SaaS platforms, and enterprise digitalization initiatives.
By end user, IT and telecom leads with a 57.0% share in 2025, driven by strong adoption of cloud platforms, virtualization, and extensive digital infrastructure to support 5G rollout and edge computing.
Regional Analysis
North America is projected to remain the largest and most dominant region in the global data center power market as it commands over 37.8% of the market share in 2025, due to its mature digital economy, dense hyperscale presence, and advanced utility infrastructure. The U.S. accounts for a significant portion of global data traffic and cloud service hosting, with cities like Northern Virginia, Silicon Valley, Dallas, and Phoenix acting as strategic data center corridors. Companies such as Microsoft, Google, Amazon, and Meta operate large-scale campuses that require continuous, redundant power supported by sophisticated UPS systems, modular PDUs, and grid-tied backup generators. The US market is projected to reach USD 8.2 billion in 2025, reaching USD 25.9 billion in 2034 at a CAGR of 13.6%.
Europe holds a substantial share, with the market projected to reach USD 3.8 billion in 2025 and anticipated to reach USD 10.7 billion by 2034 at a CAGR of 12.0%, influenced by regional sustainability mandates, stringent data governance regulations, and initiatives such as the European Green Deal encouraging energy-efficient infrastructure modernization.
Asia Pacific is the fastest-growing region, supported by rapid industrialization, expanding digital economies, and strong government initiatives promoting cloud computing and advanced data infrastructure. Countries such as Japan, South Korea, India, and China are investing heavily in hyper-scale and edge data centers. Japan's market is projected to reach USD 1.5 billion in 2025, reaching USD 6.9 billion in 2034 at a CAGR of 15.0%.
Latin America and the Middle East & Africa are gradually adopting advanced data center power solutions as digital infrastructure expands and cloud adoption increases, with Brazil, Mexico, the UAE, and Saudi Arabia emerging as key markets.
Competitive Landscape
The competitive landscape of the Data Center Power Market is defined by strategies focusing on innovation, scalability, and customer-centric solutions. Vendors prioritize R&D investments to develop high-speed, energy-efficient, and programmable power technologies. Major players include Schneider Electric, Eaton Corporation, ABB Ltd., Vertiv Holdings Co., Siemens AG, Legrand SA, Huawei Technologies Co., Ltd., Delta Electronics, Inc., General Electric (GE), Tripp Lite, Cyber Power Systems (USA), Inc., Rittal GmbH & Co. KG, Toshiba Corporation, Riello Elettronica Group, Socomec Group, AEG Power Solutions, Borri S.p.A., Cummins Inc., Kehua Tech, and Hitachi Energy.
Recent developments include TechEdge Networks' introduction of its HyperFabric Switch Series (March 2025), designed to support 800G high-speed connectivity for AI and hyperscale data centers, and CloudCore Systems' investment in an enhanced SDN Automation Platform (January 2025) focused on intent-based networking for multi-cloud and hybrid environments.
Technological Advancements
Rapid advancements in high-speed power distribution, intelligent PDUs, and software-defined power are transforming data center operations. These technologies deliver the reliability, efficiency, and scalability needed to support AI, big data analytics, and hyperscale cloud workloads.
AI-driven power automation and predictive analytics are also playing a significant role, enabling proactive issue identification, optimized load management, and enhanced security across distributed data center environments.
Consumer Adoption Patterns
Enterprises across IT and telecom, BFSI, government, healthcare, and retail and e-commerce are increasingly adopting advanced data center power solutions to support cloud migration, AI initiatives, and digital transformation. The growing availability of managed services and cloud-native power solutions is making these technologies more accessible.
Regulatory Environment
Government initiatives across regions, including U.S. cybersecurity and broadband expansion programs, Europe's GDPR and sustainability mandates, and Japan's digital infrastructure resilience efforts, shape the data center power market. Compliance with data security, energy efficiency, and sustainability regulations drives investment in modernized power infrastructure.
Market Challenges
The data center power market faces challenges related to high capital and operational costs, skills shortages, and complex power management. Additionally, the need for continuous innovation to keep pace with evolving technologies and the integration of legacy systems with modern software-defined architectures pose ongoing challenges.
Future Outlook
The future of the Data Center Power Market remains highly promising as cloud computing, AI, and edge computing continue to expand globally. Increasing adoption of 400G and 800G technologies, growth of hyperscale and edge data centers, and ongoing investment in automation and software-defined power technologies are expected to drive strong market growth during the forecast period, with the market projected to reach USD 87.4 billion by 2034 at a CAGR of 14.5%.
FAQs
What is the expected size of the Data Center Power Market in 2025?
The market is expected to reach USD 25.8 billion in 2025.
What is the projected market value by 2034?
The market is forecast to reach USD 87.4 billion by 2034.
What is the CAGR of the Data Center Power Market?
The market is expected to grow at a CAGR of 14.5% during 2025–2034.
Which component segment dominates the market?
The solution segment is anticipated to lead with approximately 62.0% share in 2025.
Which region leads the global data center power market?
North America leads with over 37.8% of the market share in 2025.
Summary of Key Insights
The global Data Center Power Market is expected to grow from USD 25.8 billion in 2025 to USD 87.4 billion by 2034, recording a CAGR of 14.5% during the forecast period. Solutions lead the component segment with 62.0% share, while software-defined power dominates technology with 58.0% share. Hyperscale data centers lead data center type with 60.0% share, IT and cloud workloads lead applications with 54.0% share, and IT and telecom lead end-user demand with 57.0% share. North America holds the largest regional share with 37.8% of global revenue in 2025, while Asia Pacific is projected as the fastest-growing region. The US market is projected to reach USD 25.9 billion by 2034 at a CAGR of 13.6%.
Purchase the Full Report
https://dimensionmarketresearch.com/checkout/data-center-power-market/